After an accident, you may receive payments from your own insurance company for medical expenses, vehicle damage, or other covered losses. If another person caused the accident, your insurer may have a right to seek reimbursement from the at-fault party or that person’s insurance company. This process is generally known as subrogation.
Subrogation can become important when you are pursuing a personal injury claim while another insurer or benefit provider has already paid some of your expenses. Understanding these rights can help you avoid surprises when negotiating a settlement or determining how much money you may ultimately receive.
The Texas Department of Insurance defines subrogation as an insurance company’s legal right to pursue another person’s insurance company after that person caused a loss to the policyholder. If you are dealing with an accident and a potential reimbursement claim, speaking with a Houston personal injury lawyer can help you understand how subrogation may affect your claim.
What Does Subrogation Mean in an Insurance Claim?
Subrogation is the legal right of an insurance company or other benefit provider to seek reimbursement from a responsible third party for payments it made on behalf of an insured person.
For example, suppose you are injured in a car accident caused by another driver. Your health insurance may pay some of your medical bills while your own auto insurance may cover certain losses under applicable coverage. If another driver was responsible, the insurers that paid those benefits may have rights to seek reimbursement from the responsible party or available insurance coverage.
The exact subrogation rights depend on the type of insurance, policy language, applicable law, and circumstances of the claim. Subrogation does not necessarily mean that you lose your right to pursue compensation. Instead, it can affect how funds are distributed after a claim is resolved.
How Does Subrogation Work After an Accident?
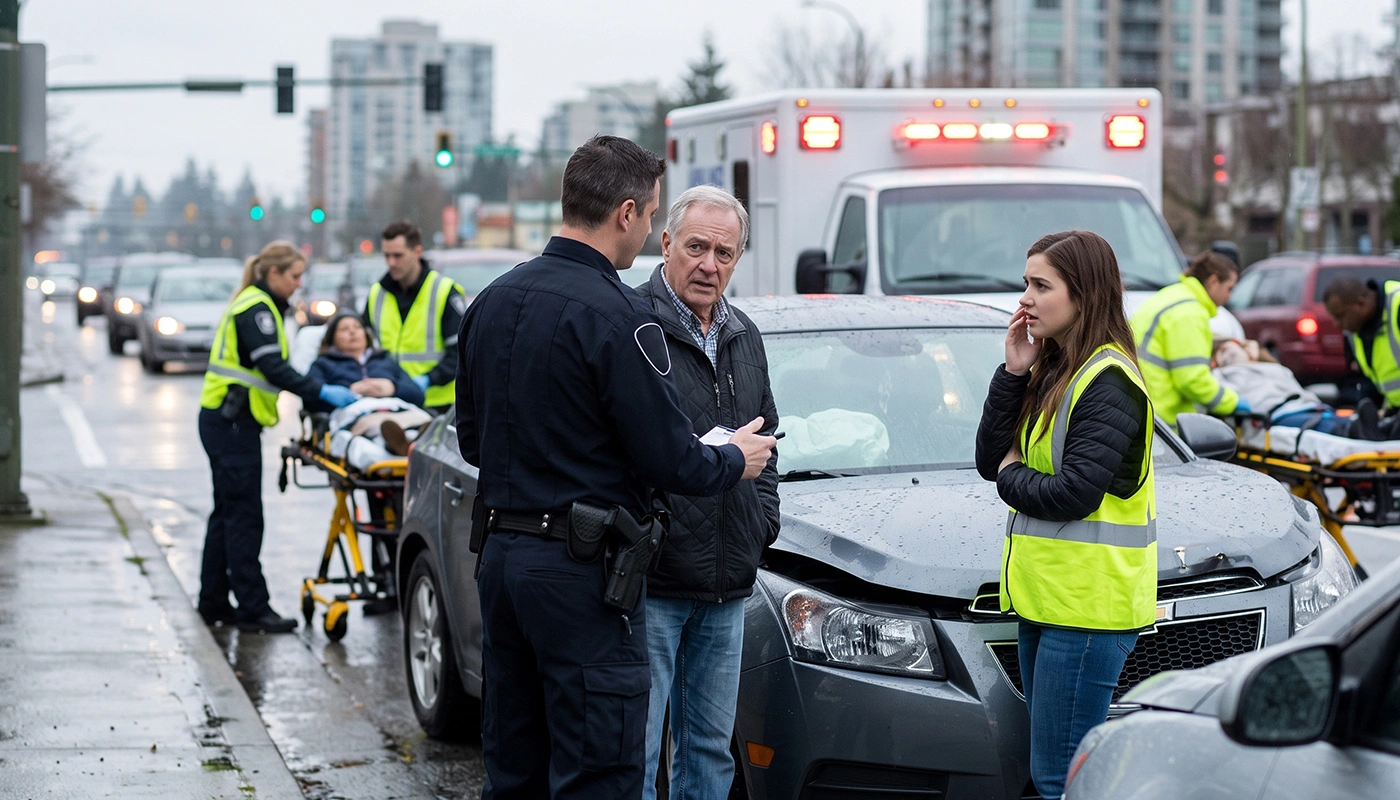
Subrogation generally begins when an insurer pays benefits for a loss that may have been caused by another party. For example, consider a Houston car accident in which another driver is at fault:
- You suffer injuries and property damage.
- Your insurance company pays benefits covered by your policy.
- You pursue a claim against the at-fault driver’s insurance.
- Your insurer identifies its potential subrogation interest.
- The insurers or attorneys determine how the claim and reimbursement rights should be handled.
- Any applicable reimbursement is addressed when the claim is resolved.
Also Read: How Do Car Accident Settlements Work in Texas
Example of Subrogation
Suppose you are injured in an accident that another driver caused. Your health insurance pays $10,000 for accident-related medical treatment. You then bring a personal injury claim against the at-fault driver and eventually recover compensation.
Your health insurer may have a contractual or legal right to seek reimbursement for some of the medical expenses it paid. The amount and enforceability of that claim depend on the applicable policy, plan, and Texas law. This does not necessarily mean that the insurer automatically receives $10,000 from your settlement. The actual amount may depend on the insurer’s rights, applicable statutes, the terms of the plan or policy, and how the claim is resolved.
What Types of Insurance Claims Can Involve Subrogation?
Subrogation can arise in several types of insurance claims, including:
- Auto insurance claims: An insurer may seek reimbursement after paying for losses caused by another driver.
- Health insurance claims: A health plan may assert rights concerning medical expenses resulting from another party’s wrongdoing.
- Workers’ compensation claims: A workers’ compensation carrier may have subrogation rights when a third party caused an employee’s injury.
- Property insurance claims: An insurer may pursue a responsible third party after paying for covered property damage.
- Other benefit claims: Certain benefit programs or plans may have reimbursement or subrogation rights depending on applicable law.
Does Subrogation Reduce Your Personal Injury Settlement?
It can, depending on the circumstances and the applicable reimbursement rights.
A subrogation claim may need to be resolved from the proceeds of a personal injury settlement or judgment if an insurer or benefit provider has a valid right to reimbursement.
However, the amount that must be reimbursed is not necessarily the same as the total amount initially paid. Various factors can affect the amount, including the applicable law, policy or plan terms, the type of benefits paid, and the circumstances of the recovery. For this reason, you should not assume that the settlement amount offered by the other party’s insurer represents the amount you will ultimately keep. A personal injury lawyer Houston can review potential reimbursement claims and help determine how they may affect the overall value of your case.
Also Read: How to Maximize an Insurance Claim in Texas
Can an Insurance Company Take Money From Your Settlement?
An insurance company may have a right to reimbursement when its policy or applicable law gives it a valid subrogation interest. However, the existence and amount of that interest depend on the circumstances. A subrogation claim is different from simply taking money from your settlement without explanation. The insurer generally must have a legal or contractual basis for its reimbursement claim.
Texas law contains specific subrogation provisions for certain situations. For example, Texas Labor Code Chapter 417 addresses subrogation rights involving workers’ compensation claims and third-party liability. The Texas Department of Insurance explains that a workers’ compensation carrier may be subrogated to an injured employee’s rights against a responsible third party. Because subrogation can involve complicated legal and contractual issues, it is important to understand the basis for any reimbursement demand before agreeing to it.
Can You Negotiate a Subrogation Claim?
In some situations, the amount of a subrogation or reimbursement claim may be negotiable, but this depends on the type of claim and applicable law.
An insurer or benefit provider may initially assert a particular amount based on the benefits it paid. However, determining the amount that can legally be recovered may require reviewing payment records, policy language, plan documents, applicable statutes, and the circumstances of the settlement.
In certain cases, attorneys may also consider the costs involved in obtaining the recovery and other factors that could affect the amount ultimately owed. You should avoid agreeing to a subrogation demand without first determining whether the amount is accurate and legally enforceable.
Does Texas Law Recognize Subrogation Rights?
Yes. Texas law recognizes subrogation rights in several contexts, but the applicable rules depend on the type of claim. For example, the Texas Workers’ Compensation Act provides statutory subrogation rights involving third-party claims. The Texas Department of Insurance states that a workers’ compensation carrier may be subrogated to an injured employee’s rights against a third party responsible for the injury. Texas insurance regulations also address subrogation in various insurance contexts. The Texas Department of Insurance, for example, provides information concerning waivers of subrogation and specific insurance policy endorsements. Because Texas does not have one universal subrogation rule that applies to every insurance claim, the specific type of coverage and claim must be considered.
What Should You Do If an Insurer Claims Subrogation?
If an insurer tells you it has a subrogation interest in your accident claim, do not ignore the notice.
Consider taking the following steps:
- Ask for documentation. Request information showing the payments made and the legal or contractual basis for the claim.
- Identify the type of claim. Determine whether the demand comes from health insurance, auto insurance, workers’ compensation, or another source.
- Review your policy or plan. The relevant policy language may explain the insurer’s rights.
- Notify your personal injury attorney. If you have legal representation, provide the subrogation notice to your attorney.
- Do not finalize a settlement without considering the claim. A settlement may need to account for valid reimbursement rights.
How Can a Personal Injury Lawyer Help With Subrogation?
Subrogation can add another layer of complexity to an already difficult personal injury claim. A lawyer can review the insurer’s demand, identify the basis for the claimed reimbursement, and evaluate how it may affect your potential recovery. An attorney may also communicate with insurers, request payment records, review applicable policy or plan provisions, and work to resolve legitimate reimbursement claims as part of the overall settlement process.
This can be particularly important when multiple insurance companies or benefit providers have paid expenses related to the same accident. If you are unsure whether an insurer has a valid claim against your settlement, consulting a personal injury lawyer near me may help you understand your options before agreeing to a settlement.
Safeguard Your Rights in Subrogation Claims
Understanding what subrogation means is important if you have received insurance benefits after an accident and are pursuing compensation from another party. An insurer may have rights to recover certain payments, but the existence and amount of a subrogation claim depend on the applicable policy, plan, law, and circumstances. If you are dealing with an accident claim and an insurer has asserted a subrogation interest, Lakhani & McGrath can help you understand how the claim may affect your settlement and explore the legal options available in your situation.